Buying a Home in Southern Maryland With 7% Mortgage Rates: What Buyers Should Know
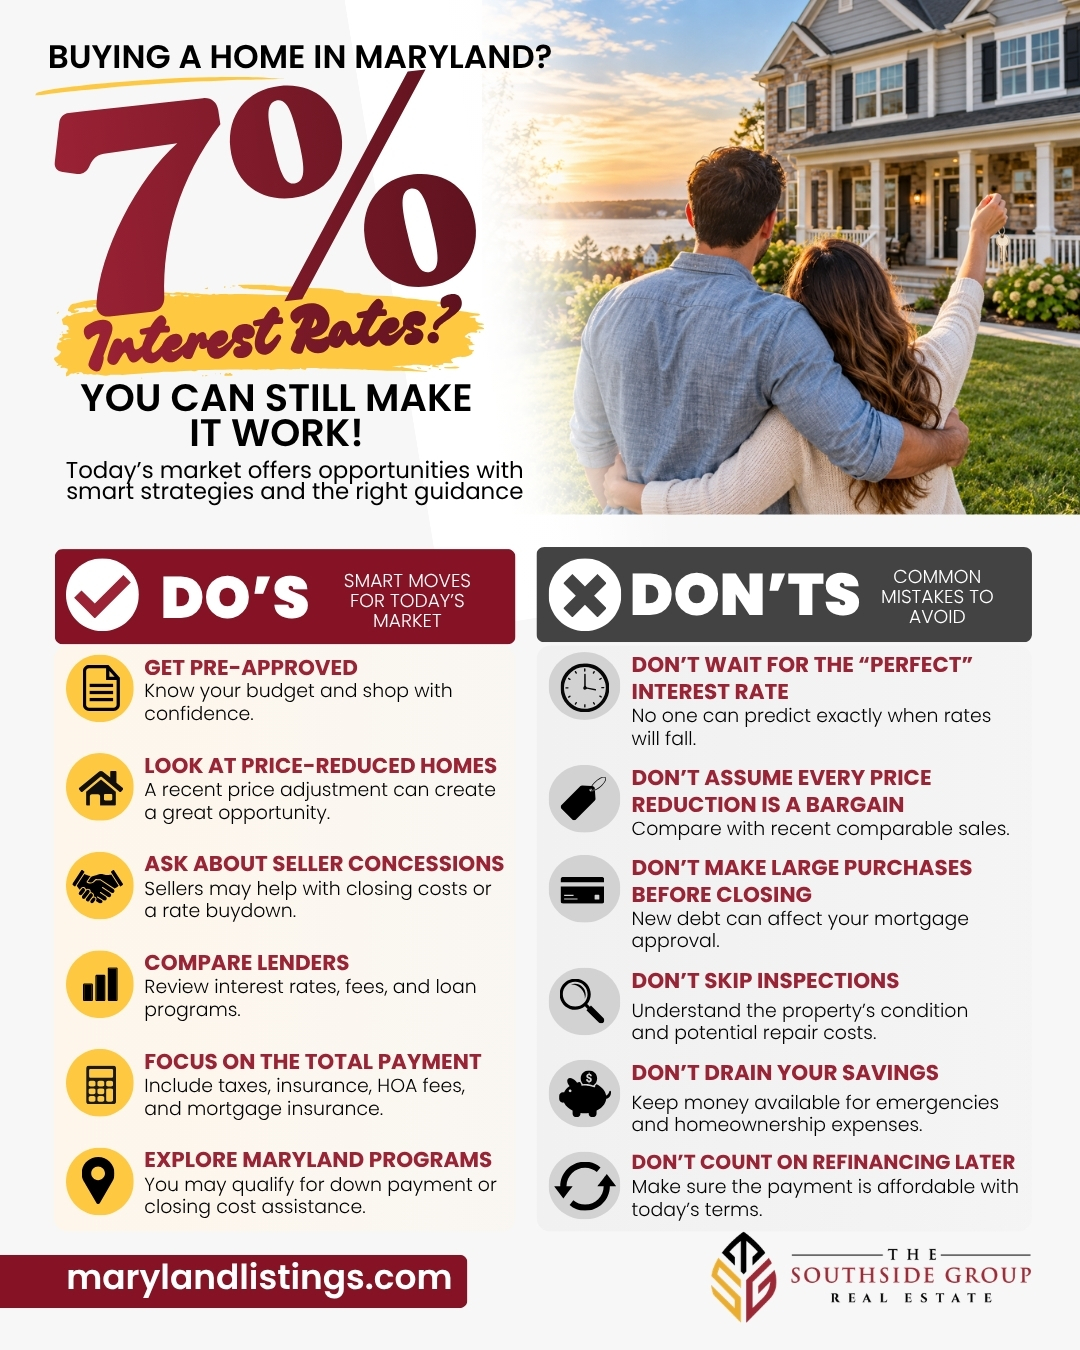
Buying a home in Southern Maryland can still be possible when mortgage rates are around 7%. Higher borrowing costs can affect your monthly payment and purchasing power, but they do not automatically mean you need to put your home search on hold.
Whether you're looking in St. Mary's, Calvert, or Charles County, the key is understanding what you can comfortably afford, evaluating properties carefully, and knowing which financing and negotiation options may be available.
Rather than trying to predict when mortgage rates will fall, focus on decisions you can control. From comparing lenders to exploring Maryland homebuyer assistance programs, a thoughtful strategy can help you approach the market with greater confidence.
Can You Still Afford to Buy a Home With a 7% Mortgage Rate?
The short answer is yes, depending on your financial situation, the home price, and the mortgage terms available to you.
A 7% interest rate is a useful example for understanding affordability, but it is not a universal or guaranteed current mortgage rate. Actual rates vary based on factors such as credit profile, down payment, loan program, lender, and market conditions.
Higher interest rates generally increase the monthly principal and interest payment on a mortgage. They can also reduce how much home you can comfortably purchase within a given budget.
Consider this hypothetical example for a 30-year fixed-rate mortgage:
|
Loan amount |
At 6% |
At 7% |
|---|---|---|
|
$250,000 |
$1,499 |
$1,663 |
|
$300,000 |
$1,799 |
$1,996 |
|
$350,000 |
$2,098 |
$2,329 |
|
$400,000 |
$2,398 |
$2,661 |
For a $300,000 loan, the difference between 6% and 7% is approximately $197 per month.
That difference matters, but the interest rate is only one part of the affordability equation.
Look at your complete monthly housing payment
Before deciding what price range works for you, consider:
-
Mortgage principal and interest
-
Property taxes
-
Homeowners insurance
-
Mortgage insurance, if applicable
-
HOA or condominium fees
-
Maintenance and future repairs
Property taxes and insurance costs can vary across Southern Maryland properties. Waterfront exposure, property characteristics, and insurance requirements may also affect the overall cost of ownership.
The goal is not simply to qualify for the largest mortgage available. It is to find a payment that fits your financial priorities.
Get Pre-Approved Before Starting Your Southern Maryland Home Search
 Mortgage pre-approval is one of the most useful steps you can take before touring homes.
A lender reviews information about your income, debts, credit, and available funds to estimate the loan amount you may qualify for. Pre-approval is not a guarantee of final mortgage approval, but it can help establish a realistic starting point.
Before shopping, consider preparing:
-
Recent income documentation
-
Bank and asset statements
-
Employment information
-
Details about existing debts
-
Information about your anticipated down payment
You can begin by reviewing the mortgage pre-approval process.
Set a comfortable budget, not just a maximum loan amount
Suppose a lender indicates that you may qualify for a $400,000 purchase. That does not necessarily mean a $400,000 home is the best financial choice.
Think about other expenses, including commuting, transportation, savings goals, and future maintenance.
For buyers considering communities around NAS Patuxent River or elsewhere in Southern Maryland, location and transportation needs can affect the overall household budget.
A practical home search starts with the payment you want to manage, not simply the highest purchase price a lender will consider.
Look Beyond the Asking Price for Buying Opportunities
A home's listing price is important, but it does not tell you everything about its value or the seller's willingness to negotiate.
Buyers should evaluate recent comparable sales, property condition, time on market, and the terms of a potential offer.
Consider price-reduced homes carefully
A price reduction may indicate that a seller is adjusting expectations. It does not automatically mean the property is a bargain.
Before making an offer, examine:
-
Comparable recently sold properties
-
The home's condition and likely repair needs
-
The original listing price and pricing history
-
Property features that may affect resale value
-
Whether the revised price is supported by local market evidence
A home with a reduced asking price can be worth exploring, but the decision should be based on the property's value rather than the size of the reduction alone.
You can browse available Southern Maryland homes to begin comparing properties and asking prices.
 Ask whether seller concessions are possible
Seller concessions are another potential negotiation tool.
Depending on the transaction, financing program, and seller's willingness, a buyer may negotiate assistance with certain closing costs or eligible financing expenses.
For example, a seller might agree to contribute toward an allowable mortgage rate buydown rather than reduce the purchase price by the same amount.
A rate buydown may lower the interest rate or payment for a defined period or, with certain discount-point arrangements, over the loan's term. The actual benefit depends on the program and cost.
Seller contributions are subject to loan-program restrictions, lender requirements, and negotiated contract terms.
Ask your lender to compare the financial impact of a price reduction, seller-paid closing costs, and any available buydown option before deciding which structure works best.
Compare Mortgage Lenders and Understand Your Loan Options
When mortgage rates are elevated, comparing lenders becomes especially valuable.
Different lenders may offer different interest rates, fees, discount-point structures, and loan programs.
Rather than focusing only on an advertised rate, request comparable Loan Estimates.
The Consumer Financial Protection Bureau provides guidance on comparing mortgage Loan Estimates.
Review the following details:
|
Mortgage feature |
Why it matters |
|---|---|
|
Interest rate |
Affects borrowing costs and payments |
|
APR |
Reflects interest and certain financing costs |
|
Discount points |
Upfront costs that may reduce the rate |
|
Closing costs |
Affect the cash needed to complete the purchase |
|
Loan term |
Influences payment amount and total interest |
|
Mortgage insurance |
May add to the monthly payment |
For a meaningful comparison, ask lenders to prepare estimates using the same loan amount, property assumptions, loan type, and comparable rate-lock conditions.
Consider available mortgage programs
Depending on eligibility, Southern Maryland buyers may explore conventional, FHA, USDA, or VA financing.
Each program has its own requirements and cost structure.
For military buyers relocating near NAS Patuxent River, VA financing may be worth discussing with a qualified lender.
The U.S. Department of Veterans Affairs explains VA-backed home purchase loans, including general eligibility and program features.
No single mortgage program is automatically the best choice for every buyer. Compare the full terms, required cash, and long-term costs.
Explore Maryland Down Payment and Closing Cost Assistance
Some buyers assume that higher interest rates mean they must save a much larger down payment before purchasing a home.
That is not always the case.
Maryland offers homebuyer financing and assistance opportunities through the Maryland Mortgage Program, administered by the Maryland Department of Housing and Community Development.
Depending on the program and eligibility, assistance may help with qualifying down payment or closing costs.
Buyers can review the Maryland Mortgage Program for available options and participating lenders.
What should you ask about assistance programs?
Before relying on any assistance in your purchase budget, ask:
-
What income or purchase-price limits apply?
-
Is homebuyer education required?
-
Must I use an approved participating lender?
-
Is the assistance a grant, loan, or another financing arrangement?
-
Are there repayment or occupancy requirements?
-
Can assistance be combined with my preferred mortgage program?
Program offerings, funding, and eligibility rules can change. Verify current details directly with the program administrator and an approved lender.
For buyers entering the market for the first time, these questions are particularly important. Additional guidance is available through our first-time homebuyer resources.
Six Homebuying Mistakes to Avoid When Interest Rates Are High
Buying a home involves several decisions beyond choosing a property. Avoiding common mistakes can help protect your finances and reduce unnecessary surprises.
1. Waiting indefinitely for the perfect interest rate
Mortgage rates are influenced by economic conditions and financial markets. No one can reliably predict exactly when rates will fall.
Waiting may be reasonable if you need additional savings, want to improve your credit, or cannot comfortably afford available payments.
However, postponing solely because you expect a specific future rate can be risky. Home prices, inventory, and financing conditions may also change.
Make your decision based on affordability and readiness rather than a rate prediction.
2. Assuming every price reduction is a bargain
A lower asking price does not necessarily mean a home is undervalued.
Compare the property with recent sales and consider whether its condition, location, or features explain the adjustment.
3. Making large purchases before closing
A new vehicle loan, financed furniture purchase, or additional credit-card balance can change your debt-to-income ratio.
Lenders may review your financial information again before closing.
Avoid taking on significant new debt or making major financial changes without discussing the potential impact with your lender.
4. Skipping property inspections without understanding the risks
An inspection can reveal concerns involving roofing, plumbing, electrical systems, heating and cooling equipment, or other components.
Even when a buyer considers a competitive offer, it is important to understand the consequences of waiving inspection protections.
Contract terms, contingencies, and property conditions should be reviewed carefully.
5. Using all your savings for the purchase
A down payment and closing costs are not the only expenses associated with homeownership.
Moving expenses, repairs, appliances, maintenance, and unexpected emergencies can arise after settlement.
Keeping an appropriate financial reserve can make the transition to homeownership more manageable.
6. Assuming you can refinance later
Refinancing may become an option if rates decline and you qualify for favorable terms.
However, there is no guarantee that rates will fall, your home's value will support a refinance, or you will meet future lending requirements.
Refinancing also may involve closing costs and other expenses.
Your mortgage should be affordable under the terms you accept today, without depending on a future refinance.
Where to Begin Your Home Search in Southern Maryland
Southern Maryland includes communities with different housing types, transportation routes, amenities, and property characteristics.
The right starting point depends on your budget, preferred property features, and daily transportation needs.
St. Mary's County
Buyers exploring St. Mary's County may consider areas such as Lexington Park, which is near NAS Patuxent River, or Leonardtown, the county seat with a historic downtown area.
Other communities, including California, Hollywood, Great Mills, and Mechanicsville, provide additional home-search options.
Property types and available inventory can vary by location.
Calvert County
Calvert County buyers may explore Prince Frederick, the county seat, along with Lusby, Saint Leonard, and surrounding communities.
Location, access to major roads, waterfront considerations, and property characteristics may influence the search.
Charles County
In Charles County, Waldorf offers access to commercial areas and major transportation routes. Buyers may also consider La Plata, Indian Head, and Charlotte Hall.
Compare specific properties rather than assuming every home within the same community has similar costs or features.
Evaluate the property and location together
As you narrow your search, consider:
-
The total monthly housing expense
-
Transportation routes and commute needs
-
Property taxes and insurance estimates
-
Home condition and maintenance requirements
-
Public amenities and services
-
Applicable HOA or condominium rules
-
Flood-zone and insurance considerations where relevant
Reviewing these factors before making an offer can help you make a more informed purchase decision.
Buying with higher mortgage rates requires preparation, but it does not have to mean abandoning your homeownership goals. The strongest approach is to understand your financing, compare the available properties, and choose a payment that works for your situation.
Find the Right Home and Financing Strategy in Southern Maryland
Buying a home with higher interest rates is about more than finding the lowest advertised mortgage rate. It's about choosing a property, financing arrangement, and monthly payment that make sense for you.
The Southside Group Real Estate helps buyers navigate home searches across St. Mary's, Calvert, and Charles counties, including military relocation near NAS Patuxent River.
If you're considering a purchase, contact The Southside Group Real Estate to discuss your home-search priorities and next steps. For personalized mortgage eligibility, loan terms, or assistance options, consult a qualified lender.
FROM OUR BLOG
Real Estate Agent Productivity: Automate, Delegate, Keep
A real estate agent's calendar can fill up quickly. Between client calls, property showings, contract deadlines, marketing, prospecting, and paperwork, it's easy to finish a busy day wondering what actually moved your business forward. The challenge isn't necessarily a lack of effort. It's how that
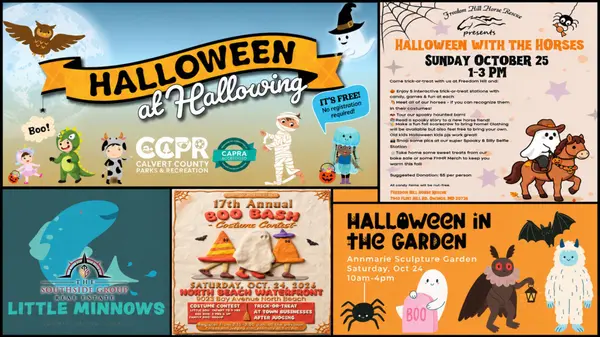
Calvert County Community Events | October 22–25, 2026
Your Weekend Guide to Halloween Fun, Fall Festivals & Family-Friendly Activities in Southern Maryland Calvert County events this weekend bring spooky Halloween adventures, colorful fall festivals, outdoor activities, and plenty of community fun to Southern Maryland from Thursday, October 22, through
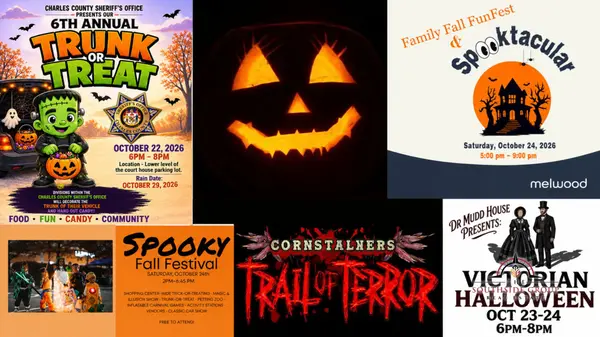
Charles County MD Events This Weekend | October 22–25, 2026
Charles County MD events this weekend are bringing Halloween thrills, fall festivals, trick-or-treating, and plenty of community fun to Southern Maryland from Thursday, October 22, through Sunday, October 25, 2026! If you've been searching for "Halloween events near me," "free things to do in Charle